Quick answer
Homeowners insurance covers a roof leak when a sudden event caused the opening — wind lifting shingles, hail, or a fallen limb — and it usually covers the resulting interior damage too. It denies leaks attributed to worn shingles, failed flashing or deferred maintenance. On an older roof the adjuster's default is wear and tear, so dated storm photos and a roofer's written causation note carry the claim. Call (888) 840-6512 to reach a certified water damage restoration company in your area; the line is answered 24/7.
Written by Marcus Reed
Reviewed by Elena VargasLicensed Public Adjuster (TX, FL, LA)
Reviewed August 13, 2026· Next review Feb 2027
The Line Adjusters Draw
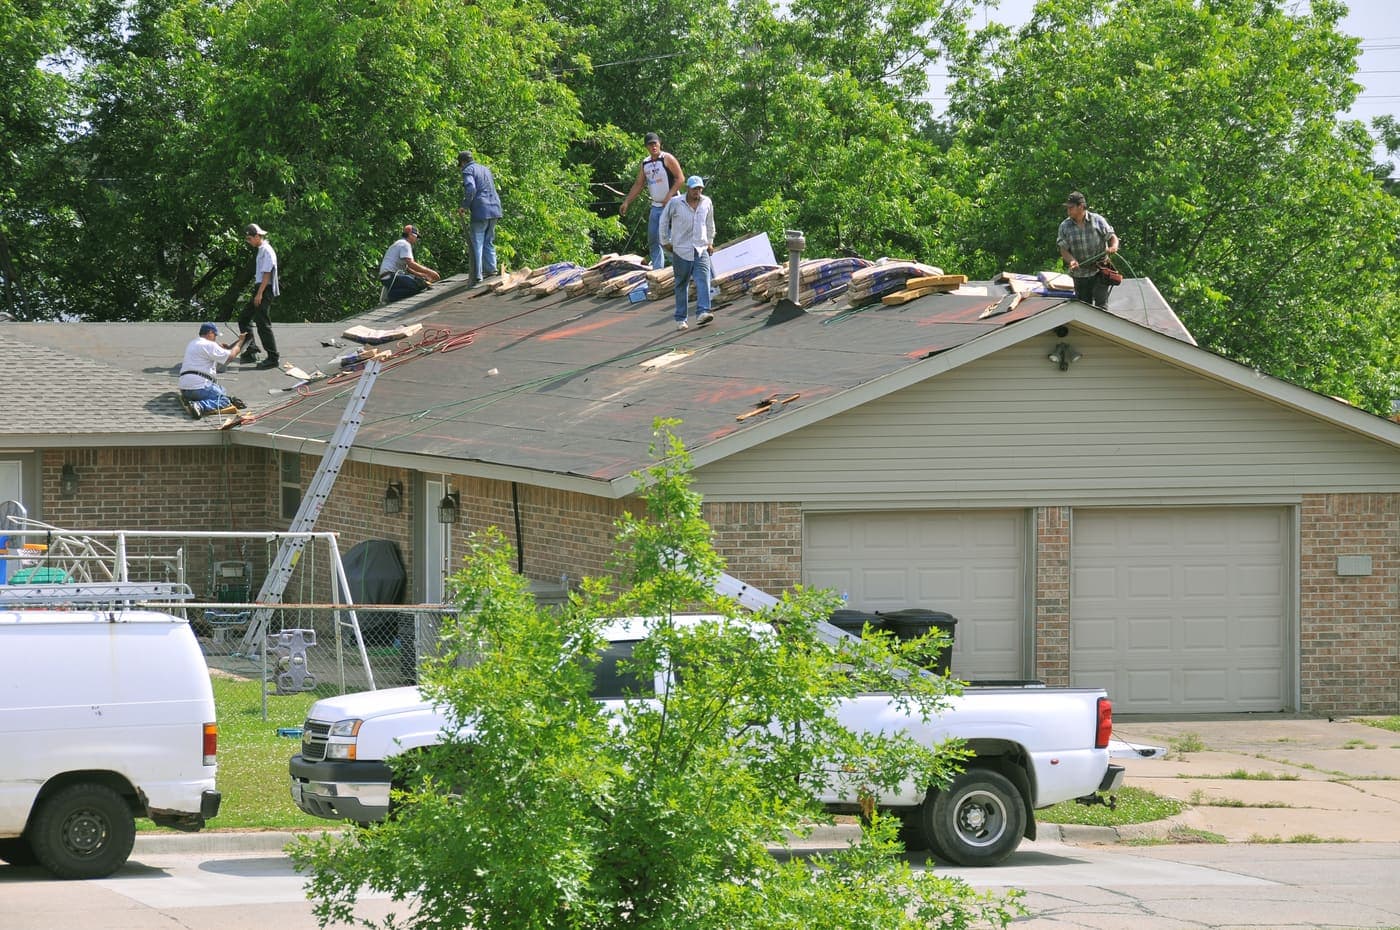
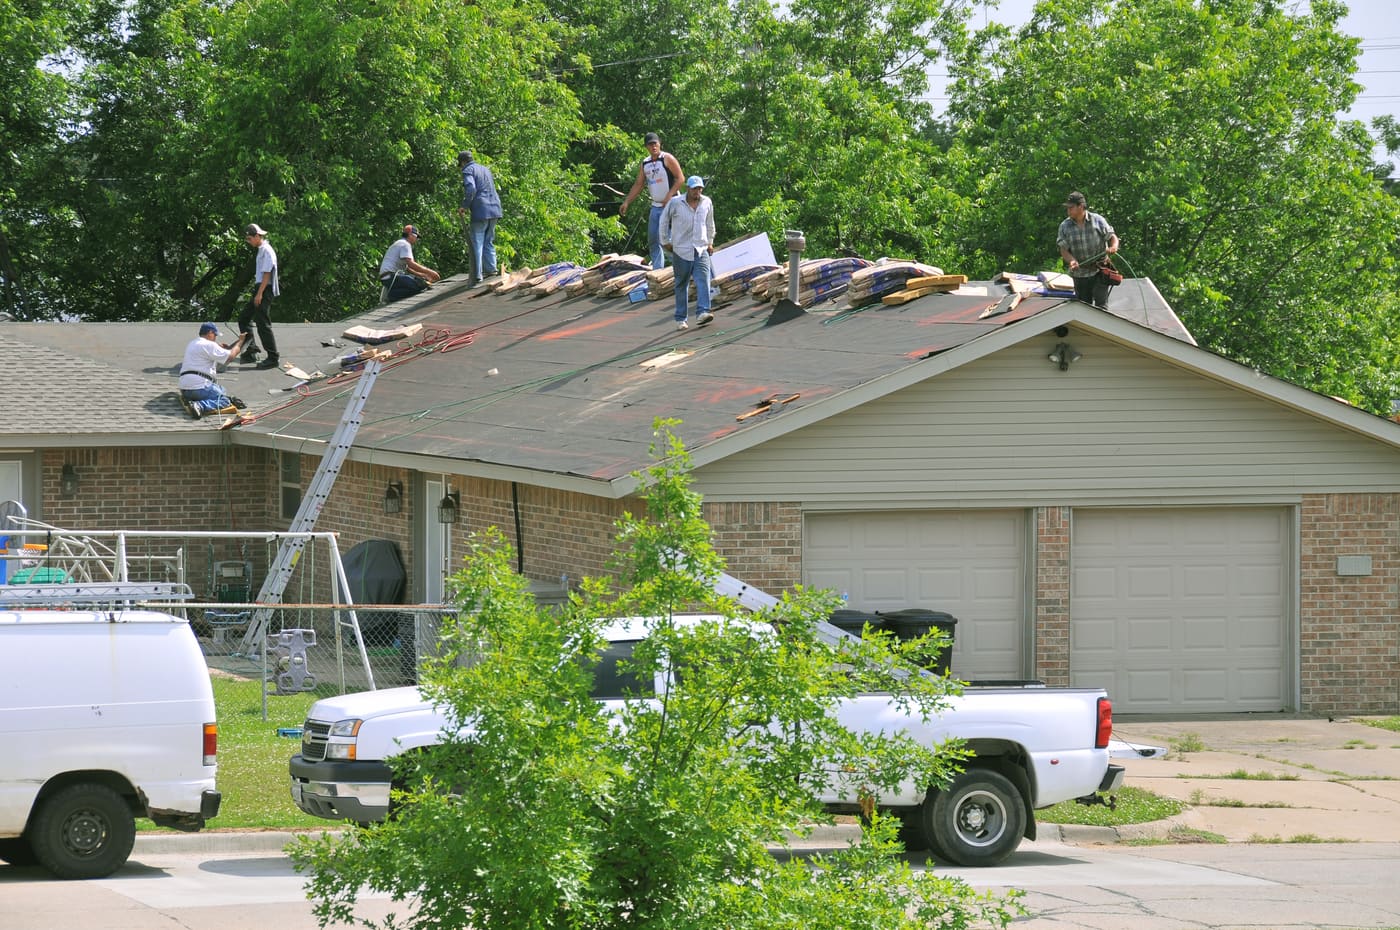
Homeowners insurance covers sudden, accidental roof openings: wind lifting shingles, hail strikes, a limb through the decking. It excludes gradual causes: worn shingles, aged flashing, failed sealant, deferred maintenance. Every roof leak claim is decided by which side of that line the adjuster places the cause — and the same wet ceiling can sit on either side.
Two consequences follow. First, evidence of the sudden event is worth more than evidence of the damage. Second, an old roof doesn't void coverage, but it moves the burden of proof onto you — on a 20-year roof, "wear and tear" is the adjuster's default until the storm evidence argues otherwise.
The Part Most Homeowners Miss
The claim usually has two components: the roof opening itself, and the resulting interior damage — ceiling drywall, insulation, flooring, repainting. When the roof cause is covered, the interior follows. And even when the roof repair is denied as maintenance, some policies still cover the interior water damage as ensuing loss. Read a denial letter's exact scope before assuming it closed both doors.
Also check how your policy pays roofs: many now schedule older roofs at actual cash value — depreciated — rather than replacement cost, and storm states often carry separate wind/hail deductibles of 1–2% of your dwelling coverage. A $1,500 repair under a $4,000 percentage deductible is a claim not worth filing; document it anyway in case the damage grows.
Build the Causation File
The order matters — evidence first, repairs second:
- 1Exterior photos of missing or creased shingles, dented vents, the fallen limb — dated, from the ground and (only if safe) a ladder
- 2Interior trail — attic sheathing, insulation, stains, drips, every affected room
- 3Weather record — save the wind/hail report for your address and date; it ties damage to a named event
- 4Mitigation — tarp the opening, move contents, keep every receipt (reimbursable, and required by the policy)
- 5A roofer's written causation note — one line like "wind-lifted shingles consistent with the storm of [date]" is the most persuasive document a disputed file can hold
File against the storm date, not the day you noticed the stain — late discovery is normal and should be described as exactly that.
If the Answer Is No
Maintenance denials are among the most appealable, because they rest on an opinion about causation — and opinions can be out-argued with dated photos, weather data, and a professional assessment. Request the denial in writing with the specific policy language cited, then build against that language. Our claim-denial appeal guide walks the full sequence.
Need a contractor your insurer accepts?
Claims live or die on documentation. Crews that estimate in Xactimate and log moisture readings give adjusters what they need.
(888) 840-6512- Describe the loss and where the claim stands
- You're routed to a crew that documents for insurers
- They scope it in writing — you decide, no obligation
Covered or Excluded, by Scenario
| Scenario | Covered? |
|---|---|
| Wind lifts or tears off shingles; rain enters | Yes — sudden opening from a covered peril |
| Hail cracks shingles or punctures the membrane | Yes (hail deductible may apply) |
| A tree or limb falls through the roof | Yes, including debris removal up to a limit |
| Ice dam backs water up under shingles | Usually yes, as sudden water damage from a covered event; ice dam removal and prevention |
| Flashing that corroded and separated over years | No — wear and tear |
| Shingles at the end of their life, granule loss, curling | No — age and maintenance |
| A roof installed wrong that leaked at the first rain | No — workmanship; claim against the installer |
| Leak known for months, painted over, then claimed | No — neglect and gradual damage |
| Hurricane wind damage | Yes, but subject to a separate hurricane or named-storm deductible (often 2–5% of dwelling coverage) in coastal states |
| Mold that grew from the leak | Only if the leak is covered, and only up to the mold sublimit (details) |
Roof Age and How the Roof Is Paid
Many policies now pay roofs on a schedule: a roof under a certain age is paid at replacement cost, older roofs at actual cash value — the depreciated figure — sometimes down to a percentage floor. A 17-year-old asphalt roof on an ACV schedule may be paid at 30–40% of the cost of a new one, even for a covered wind loss. Check the declarations page for a roof surfacing payment schedule or an ACV roof endorsement; it is the single most common surprise on a roof claim. The interior damage — ceiling, insulation, floors — is usually still paid at replacement cost, because it is not the roof.
Emergency Tarping and What It Costs
The policy requires you to prevent further damage, and it pays reasonable costs to do so. A professional emergency tarp runs $200–$800 depending on roof size and pitch; a roofer's temporary repair $150–$500; interior mitigation (drying the attic and ceiling) is priced like any water loss. Keep every receipt and photograph the roof before the tarp goes on. Do not go on a wet or steep roof yourself; a fall is not covered by anything useful.
The Interior Claim Is Often the Larger One
A wind loss that opens a small section of roof can put water through the attic insulation, the ceiling drywall, and the floor below, and that interior claim is often several times the roof repair. Roof leak ceiling damage covers reading the stain and stopping the drip; water damaged drywall repair the fix. File both parts on the same claim, with the storm date as the date of loss, and get the attic inspected — wet insulation that is not replaced becomes the mold sublimit conversation a season later.
Reading to confirm what you already suspect?
Confirm it in two minutes instead — the pro on this line answers questions about YOUR situation all day: what it is, what it should cost, whether you even need service. If you want, they'll set the appointment on the same call.
Toll-free · no obligation · asking costs nothing
Frequently Asked Questions
Will homeowners insurance cover a roof leak?
Covered when the leak traces to a sudden, accidental event: wind lifting shingles, hail strikes, a falling branch. Not covered when the adjuster attributes it to gradual causes — worn-out shingles, old flashing, failed sealant, or deferred maintenance.
The interior water damage that results from a covered roof opening is typically covered too, which is often worth more than the roof repair itself.
Will insurance cover a roof leak on an old roof?
Age alone doesn't void coverage, but it moves the burden: on a 20-year-old roof the adjuster's default is 'wear and tear' unless the storm evidence is clear.
Some policies also pay older roofs at actual cash value (depreciated) rather than replacement cost — check for a roof payment schedule in your policy. Dated photos of the roof's pre-storm condition are the strongest counterweight.
Does insurance cover the ceiling damage from a roof leak?
If the roof opening itself is covered, the resulting interior damage — ceiling drywall, insulation, flooring, paint — is normally covered as ensuing loss.
Even when the roof repair is denied as wear-and-tear, some policies still cover the interior water damage; read the denial letter's exact scope before accepting it covers everything.
Should I file a claim for a small roof leak?
Compare the realistic payout against your wind/hail deductible — many policies in storm states carry percentage deductibles (1–2% of dwelling coverage) that swallow small claims.
A $1,500 repair against a $4,000 deductible is a no. But document the damage fully anyway: if the leak grows or the storm produced hidden damage, your dated evidence preserves the bigger claim.
What if my roof leak claim is denied?
Denials on 'maintenance' grounds are among the most appealable — the insurer's conclusion is an opinion about causation, and opinions can be rebutted with evidence: dated photos, weather reports for your address, a roofer's written causation assessment, and a second inspection.
Request the denial in writing with the specific policy language cited, then build your file against that language.
Who do I call right now for water damage?
Call (888) 840-6512. The line is answered 24 hours a day, seven days a week, and connects you with an IICRC-certified water damage restoration company that serves your area. Describe what you can see — where the water is coming from, how long it has been there, and whether it smells — the more specific you are, the faster the right company is on the line.
If the source is a pipe or an appliance, shut the main water valve first. Have four things ready and the call goes quickly: the address, when the water started, what is wet now, and whether you have filed an insurance claim.
Need it handled now?
Roof Leak Water Damage — 24/7 Certified Crews
Ceiling stains spreading? Document for the claim, then dry the structure before mold complicates it.
Sources
- III — Homeowners Insurance Basics(retrieved 2026-08-13)
- NAIC — Filing a Homeowners Claim(retrieved 2026-08-13)
Methodology: How we source and verify data · Report an error
Disclaimer: HearthDry is an independent educational resource. This article is for informational purposes only and does not constitute professional, legal, or insurance advice. Consult licensed professionals before making decisions about your property or insurance claims.
Professional Equipment
Document Moisture Like an Adjuster
A moisture meter puts numbers on 'the ceiling is wet' and a thermal camera maps how far water traveled inside walls — both make a claim file adjusters take seriously.
Affiliate link — HearthDry earns a commission from Sylvane via CJ at no extra cost to you
Free 2-day shipping
Amazon Prime members pay no shipping on restoration equipment
Dehumidifiers, air movers, and moisture meters qualify for free Prime delivery — bulk items that otherwise cost $15–$40 to ship.
Affiliate link — HearthDry earns a bounty if you sign up; costs you nothing extra.
Equipment
What each machine actually does
Removes the moisture the structure is still giving off — the machine that decides how long drying takes
See the picks →Moves air across wet surfaces so the dehumidifier has something to take out of the air
See the picks →Finds water behind walls and under floors, and tells you when a material is actually dry
See the picks →Alerts you the moment a leak starts — the cheapest thing on this list and the only preventive one
See the picks →Those pages carry affiliate links. As an Amazon Associate, HearthDry earns from qualifying purchases; it costs you nothing extra.
Our Amazon storefront →Advertisement