Written by Marcus Reed
Reviewed by Elena VargasLicensed Public Adjuster (TX, FL, LA)
Reviewed September 4, 2026· Next review Mar 2027
Quick answer
Homeowners insurance pays for water damage that is SUDDEN AND ACCIDENTAL — a burst pipe, a failed supply line, a ruptured water heater — including the tear-out, drying and rebuild it causes. It excludes what it considers preventable or separate: gradual leaks and seepage ('maintenance'), outside floodwater (separate NFIP/private flood policy), and sewer backups unless you carry a specific rider. Mold is covered only when it RESULTS from a covered sudden loss, and usually under a capped rider ($1,000–$10,000 typical). Claims are won on documentation: timestamped photos before cleanup, fast mitigation, and a certified crew's moisture logs to the S500 standard — the exact package adjusters are trained to trust. Call (888) 840-6512 to reach a certified water damage restoration company in your area; the line is answered 24/7.
Sound like your situation? Confirm it in one call instead of ten more minutes of reading — (888) 840-6512 · toll-free · no obligation
Three Words Decide Everything
Homeowners policies pay for water damage that is sudden and accidental. Every coverage fight you will ever have lives inside those three words: the insurer arguing the damage was gradual, foreseeable or maintenance — you demonstrating it was abrupt, accidental and mitigated fast. Understand that frame and the rest of this guide is tactics.
The Coverage Map
| Situation | Covered? | The catch |
|---|---|---|
| Burst supply pipe | Usually yes | Frozen bursts require heat was maintained |
| Appliance / water heater failure | Usually yes | The worn-out unit itself isn't paid for |
| Roof leak from storm damage | Usually yes | Wear-and-tear roof leaks are excluded |
| Slow leak / seepage | Usually no | The 'gradual damage' exclusion — see below |
| Sewer or drain backup | No by default | Cheap rider adds it — check your policy TODAY |
| Outside floodwater | Never | Separate NFIP or private flood policy only |
| Mold | Conditionally | Only from covered losses, usually capped $1k–$10k |
Two lines in that table save the most homeowners the most money: the sewer backup rider (often under $150/year, discovered missing at the worst possible moment) and the mold cap (fast documented drying after any water event is what keeps you out of the capped peril entirely).
The Gradual-Damage Battleground
'Gradual' is the insurer's favorite word because slow leaks genuinely are excluded — and because the label gets stretched. Two counters matter:
- 1Sudden failure, slow discovery. A fitting that let go inside a wall is a sudden loss even if you found it two weeks later. Many states and policies treat *hidden* leaks — inside walls, under slabs, behind appliances — more favorably precisely because no reasonable homeowner could have caught them.
- 2The mitigation record. Nothing rebuts 'you neglected this' like a same-day restoration call, timestamped discovery photos and a certified crew's origin assessment naming the failure point.
The Claim, Step by Step
- 1Mitigate immediately — it's a duty, not a courtesy. Policies require you to prevent further damage. Stopping the source and starting professional drying protects the claim; waiting for an adjuster before drying creates the mold that becomes a second fight.
- 2Document in parallel. Photos and video before cleanup, the water line, every room, damaged items with values. Save the failed part — the burst hose or fitting is physical evidence.
- 3Report within 24 hours. Get the claim number and ask three questions: my deductible? additional living expenses if needed? is there a mold cap or sewer rider on my policy?
- 4Meet the adjuster with the package. Photo timeline, moisture map, drying logs. Adjusters scope what they can verify — hand them verification.
- 5Compare scopes line by line. Disputes are almost always missing line items (contents, extra drying days, code upgrades), not unit prices — both sides usually price from the same Xactimate tables.
- 6Escalate in writing. Lowball or denial: supervisor review → state insurance department complaint → the policy's appraisal clause → public adjuster or counsel. Every rung works better with the paper trail attached.
Need a contractor your insurer accepts?
Claims live or die on documentation. Crews that estimate in Xactimate and log moisture readings give adjusters what they need.
(888) 840-6512- Describe the loss and where the claim stands
- You're routed to a crew that documents for insurers
- They scope it in writing — you decide, no obligation
The Four Common Denials — and the Responses
- “Gradual damage.” Show suddenness (the failed part, the flood pattern) or hiddenness (location no inspection would catch), plus your same-day mitigation record.
- “Maintenance issue.” Separate the cause from the consequence: the worn washer hose isn't covered — the sudden discharge it released is. Policies pay for resulting damage.
- “Late reporting.” Document the discovery date (that's what starts the clock, not the failure date) and every prompt step after it.
- “Scope disagreement.” Not a denial at all — a negotiation. The certified crew's S500 documentation versus a desk estimate is a winnable comparison; invoke appraisal if it stalls.
When to Bring a Public Adjuster
Their 10–15% earns itself on large or complex losses, on denied claims where your documentation is solid but leverage isn't, and whenever the insurer's number sits tens of thousands below the certified scope. Skip them for small contained claims near your deductible. License-check them like any contractor — your state's registry habit applies here too.
Rates, Renewals and the CLUE Database
Insurers share claim history through CLUE for seven years. One documented sudden loss rarely moves your world; a pattern does. The playbook: claim the real losses, self-absorb the trivial ones, and after any claim, put prevention on paper — braided steel hoses, a smart shut-off valve, a sump with battery backup. Renewal conversations go differently when the file shows the fix.
Where the Restoration Call Fits
Every strong claim in this guide has the same spine: a certified crew's documentation. That's the practical order of operations — source stopped, photos taken, certified drying moving the same day, insurer notified with a claim number by evening. One call starts that spine 24/7, with the scope and costs explained before anything is agreed — and everything the crew logs from that moment forward is working for your claim.
Reading to confirm what you already suspect?
Confirm it in two minutes instead — the pro on this line answers questions about YOUR situation all day: what it is, what it should cost, whether you even need service. If you want, they'll set the appointment on the same call.
Toll-free · no obligation · asking costs nothing
Frequently Asked Questions
- 1gradual damage — slow leaks and seepage the insurer says you should have caught
- 2flood — surface water entering from outside is NEVER homeowners coverage, it's a separate NFIP or private flood policy
- 3sewer/drain backup — excluded by default, covered by a cheap rider most people don't know exists
- 4maintenance and wear — the failed part itself (the old water heater, the worn hose) isn't paid for even when the damage it caused is.
- 1timestamped photos/video of the source and every damaged area BEFORE cleanup
- 2proof of fast mitigation — receipts, the restoration call time
- 3a certified crew's moisture map and daily drying logs to the S500 standard
- 4an inventory of damaged items with photos and approximate values
- 5every communication in writing. Gaps in this chain are where 'gradual damage' denials grow.
What water damage does homeowners insurance actually cover?
The covered family is sudden-and-accidental discharge: burst or leaking supply pipes (including frozen bursts if heat was maintained), appliance and water heater failures, accidental overflows caught reasonably fast, and roof leaks caused by a covered peril like storm damage.
Coverage typically includes emergency mitigation, drying, tear-out and rebuild of damaged structure, and often additional living expenses if the home is uninhabitable.
What's excluded — and what do the exclusions really mean?
Four standard exclusions:
Is mold covered by insurance?
Only conditionally: mold RESULTING from a covered sudden water loss is generally covered — but usually under a mold-specific cap or rider, commonly $1,000–$10,000, well below what a serious remediation costs.
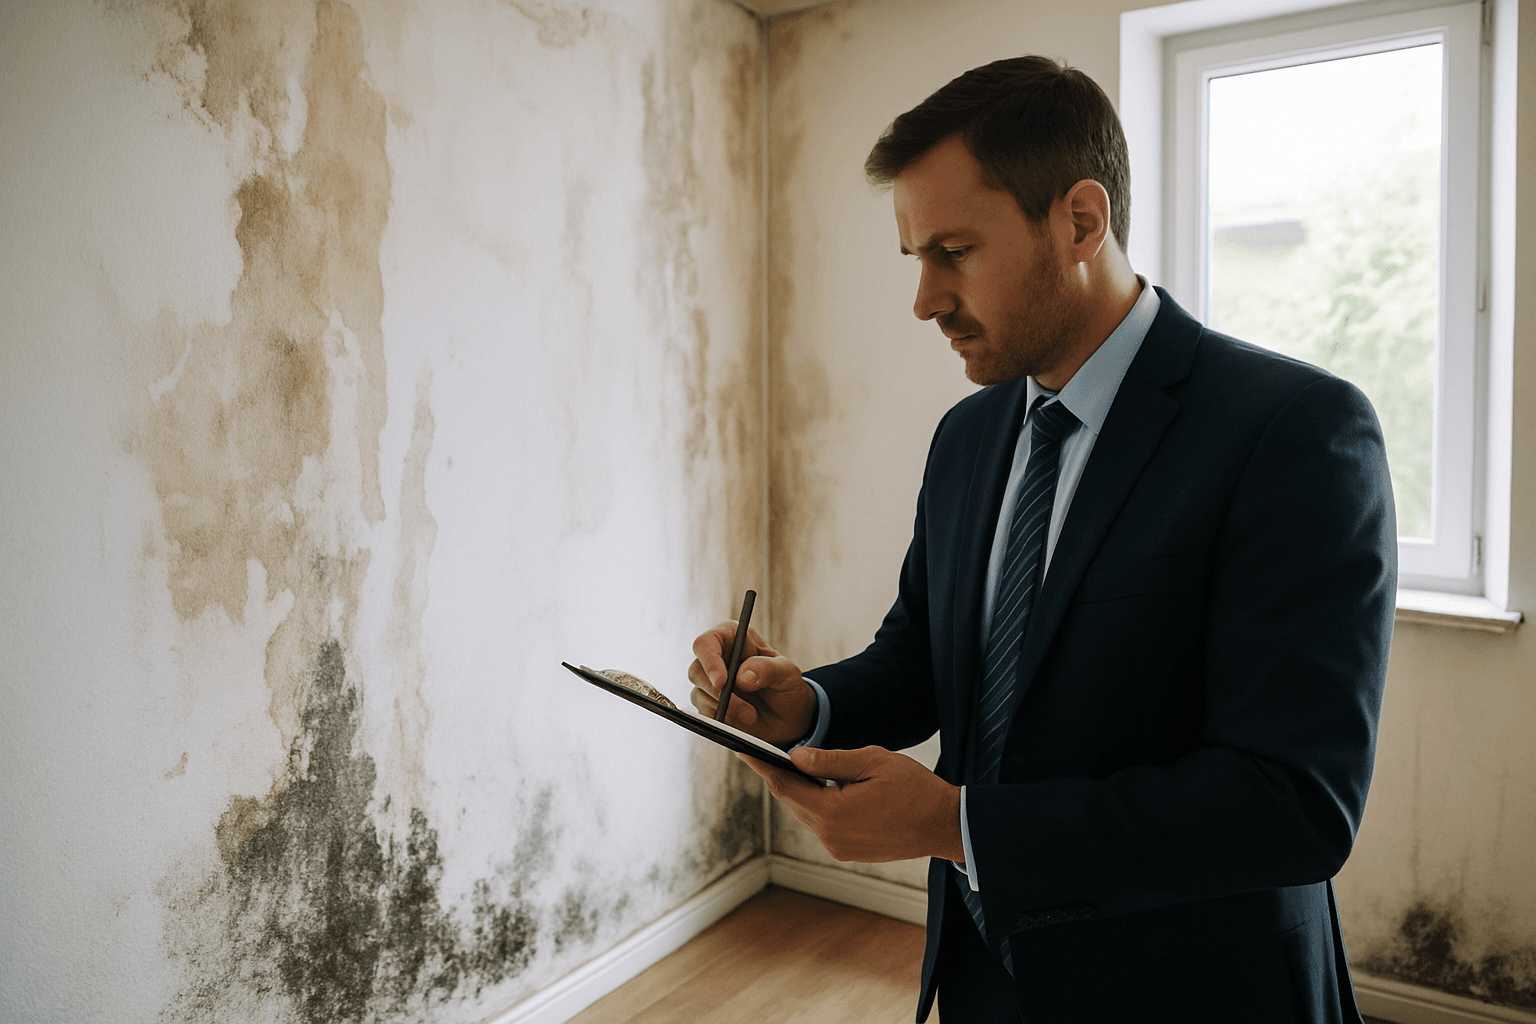
Mold from humidity, condensation or slow leaks is excluded as maintenance. The practical lesson: fast, documented drying after any water event is also insurance strategy, because it prevents the capped peril entirely.
What documentation actually wins claims?
The package adjusters trust:
Should I call the insurer or the restoration company first?
Stop the water, then start mitigation — most policies REQUIRE you to prevent further damage, so getting drying moving is protecting the claim, not jumping the line. Report the claim the same day.
What not to do: wait days for an adjuster before any drying (the mold that grows meanwhile becomes a fight), or authorize full reconstruction before the adjuster's scope.
The adjuster denied my claim as 'gradual damage' — is that final?
NoDenials are opening positions, not verdicts.
Respond with evidence targeting the reason: for 'gradual', show the failure was sudden (the burst fitting itself, the flooding pattern) or genuinely hidden (inside a wall, behind an appliance — many states treat hidden leaks more favorably); add the certified crew's origin assessment; request the denial's specific policy language in writing. Escalation ladder: supervisor review, state insurance department complaint, appraisal clause, public adjuster or attorney.
When is a public adjuster worth their 10–15%?
Three situations: large complex losses (multi-room, reconstruction) where scope disputes are expensive; a claim already denied or lowballed where you have documentation but no leverage; and any loss where the insurer's number is tens of thousands below the certified crew's scope.
For small contained claims, their fee usually outweighs the lift. Verify state licensing before hiring — the license lookup habit applies here too.
Will filing a water claim raise my rates or get me dropped?
One well-documented sudden-loss claim rarely triggers drastic action; patterns do — multiple water claims in a few years mark a property as high-risk in the CLUE database that insurers share.
Strategy: file the real losses, self-pay the trivial ones near your deductible, and after any claim, document the repairs and prevention upgrades (braided hoses, shutoff valve, sump) — they help at renewal.
Who do I call right now for water damage?
Call (888) 840-6512. The line is answered 24 hours a day, seven days a week, and connects you with an IICRC-certified water damage restoration company that serves your area.
Describe what you can see — where the water is coming from, how long it has been there, and whether it smells — and the dispatcher routes you to a crew that handles that kind of loss. If the source is a pipe or an appliance, shut the main water valve first; the call itself takes under two minutes.
Sources
- IICRC S500 Standard for Professional Water Damage Restoration
- III — Water damage and homeowners insurance
- EPA — Mold Cleanup in Your Home
Methodology: How we source and verify data · Report an error
Disclaimer: HearthDry is an independent educational resource. This article is for informational purposes only and does not constitute professional, legal, or insurance advice. Consult licensed professionals before making decisions about your property or insurance claims.
Equipment
What each machine actually does
Removes the moisture the structure is still giving off — the machine that decides how long drying takes
See the picks →Moves air across wet surfaces so the dehumidifier has something to take out of the air
See the picks →Finds water behind walls and under floors, and tells you when a material is actually dry
See the picks →Alerts you the moment a leak starts — the cheapest thing on this list and the only preventive one
See the picks →Those pages carry affiliate links. As an Amazon Associate, HearthDry earns from qualifying purchases; it costs you nothing extra.
Advertisement